Generational wealth isn't built in a single generation of income — it's built through deliberate systems: earning, saving, investing, protecting, and transferring assets in a way that compounds across decades and family members. This guide walks through the process in order.
Step 1: Build a Foundation (Stabilize Your Own Finances First)
You can't build wealth for future generations if your own finances are unstable.
- Get out of high-interest debt. Credit cards and payday loans (15–25%+ APR) destroy compounding faster than most investments can outpace it.
- Build an emergency fund. 3–6 months of essential expenses in a liquid, high-yield savings account. This prevents you from liquidating investments or going into debt during a crisis.
- Get adequate insurance. Health, disability, and (once you have dependents) term life insurance. A single uninsured event can wipe out a decade of savings.
- Track your net worth annually. You can't manage what you don't measure. A simple spreadsheet (assets minus liabilities) is enough to start.
Step 2: Maximize and Diversify Income
Wealth is built from the gap between what you earn and what you spend, multiplied by what you do with the surplus.
- Grow your primary income. Negotiate salary, build in-demand skills, or move roles/industries when it meaningfully increases earning potential.
- Build additional income streams. A side business, freelance work, or rental income diversifies your cash flow so no single job loss threatens the whole plan.
- Keep lifestyle inflation in check. As income rises, resist proportionally raising fixed expenses (housing, cars, subscriptions). The gap between income and spending is what funds every step below.
Step 3: Save and Invest Consistently
This is the compounding engine of generational wealth.
- Automate saving/investing. Treat it like a non-negotiable bill — a fixed percentage of every paycheck, automatically invested before it hits your checking account.
- Use tax-advantaged accounts first. In the U.S., this generally means employer retirement plans (especially with a match), IRAs, and HSAs, before taxable brokerage accounts. (Rules vary by country — check your local equivalents.)
- Diversify across asset classes. Common building blocks include:
- Broad-market index funds/ETFs (low-cost, diversified equity exposure)
- Real estate (primary residence, rental property, or REITs)
- Bonds/fixed income (stability and income, especially as you age)
- A business or business equity (often the single largest wealth driver for families that build it)
- Reinvest returns. Dividends, rental income, and business profits reinvested — rather than spent — are what turn linear savings into compounding growth.
Note: The right mix of assets depends on your timeline, risk tolerance, and goals. This is general information, not personalized investment advice — a fee-only fiduciary financial advisor can help tailor a plan to your situation.
Step 4: Protect What You Build
Wealth that isn't protected can disappear in a single lawsuit, divorce, illness, or bad decision.
- Umbrella liability insurance once your net worth grows beyond what standard auto/home policies cover.
- Proper business structuring (LLC, corporation, etc.) to separate personal and business liability if you own a business.
- Estate planning documents:
- A will (minimum baseline — dictates who gets what)
- A durable power of attorney and healthcare directive (so someone can act for you if you're incapacitated)
- A trust, if appropriate — trusts can avoid probate, reduce estate taxes, and control how and when heirs receive assets (e.g., staged distributions rather than a lump sum at 18)
- Beneficiary designations on retirement accounts and life insurance — these override your will, so review them after every major life event (marriage, divorce, birth, death).
Estate and trust structures are legal instruments with real tax and legal consequences — this is general information, not legal advice. An estate attorney should draft or review these documents.
Step 5: Minimize Wealth Transfer Taxes and Costs
How wealth passes between generations matters as much as how much wealth exists.
- Understand estate/inheritance tax thresholds in your jurisdiction — many families with substantial estates use trusts, gifting strategies, or life insurance to reduce the tax bite.
- Use annual gift exclusions where available to transfer wealth incrementally during your lifetime rather than all at once at death.
- Step-up in basis and other tax mechanics (in the U.S., inherited assets often get a "stepped-up" cost basis) can significantly affect whether it's better to gift assets now or pass them at death — this is highly situation-specific.
- Avoid probate costs and delays where possible through beneficiary designations, joint ownership, or trusts.
Tax law changes frequently and varies enormously by country and even by state/province — consult a tax professional or estate attorney before making transfer decisions.
Step 6: Invest in Education and Human Capital
The most durable form of generational wealth is often the next generation's ability to create and sustain wealth themselves.
- Fund education deliberately (e.g., education savings accounts) — but balance this against your own retirement security; you can borrow for education, not for retirement.
- Teach financial literacy early and explicitly. Budgeting, investing basics, debt, and the value of compounding are rarely taught in school — most wealthy families treat this as a parenting responsibility, not an assumption.
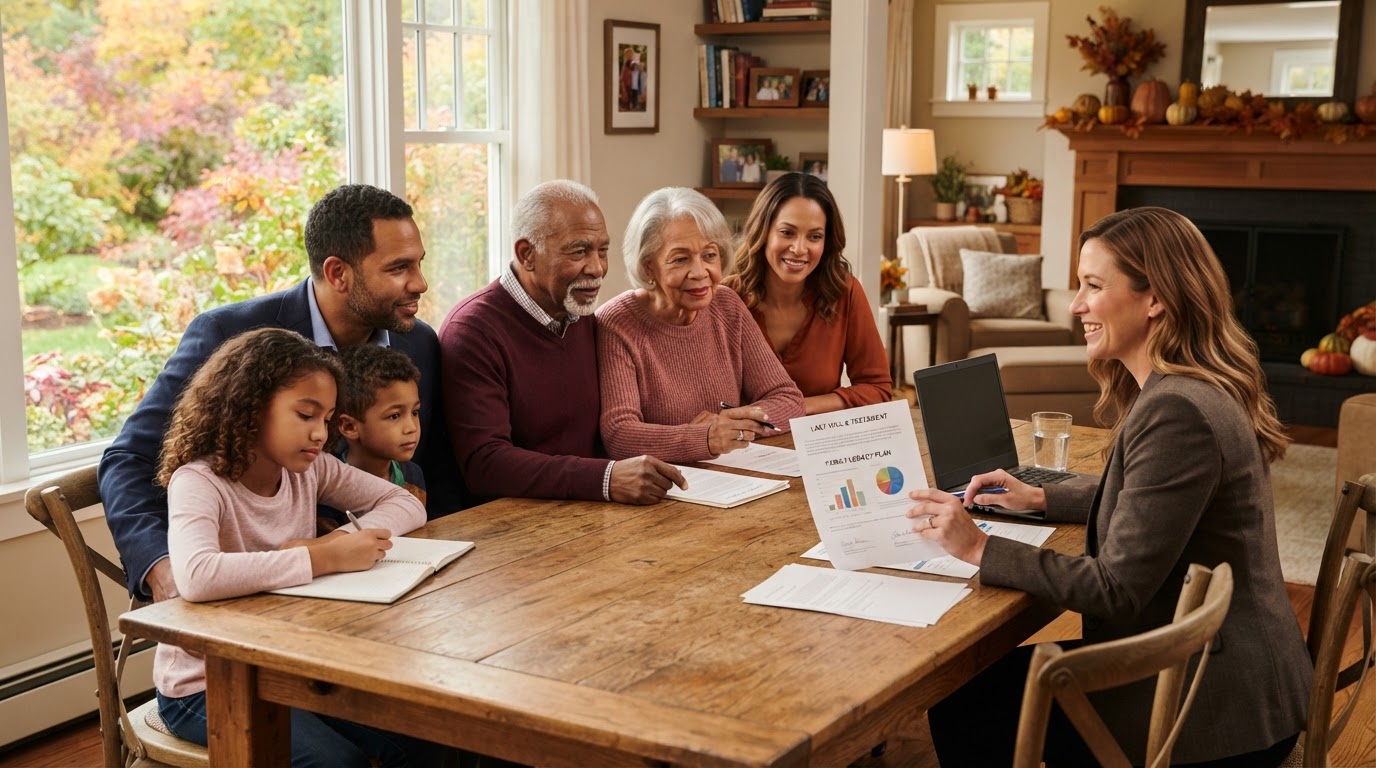
- Give heirs real experience with money before they inherit it — a part-time job, a small investment account they manage, or involvement in family financial discussions.
Step 7: Build (or Buy Into) Assets That Outlast You
Passive savings alone rarely create generational wealth — ownership does.
- Business ownership — starting, buying, or holding equity in a business is historically one of the fastest wealth accelerators, though it carries real risk and requires real skill/time.
- Real estate — property can generate income, appreciate, and be passed down or leveraged across generations.
- Long-term equity ownership — holding diversified stock investments for decades (not trading them) captures long-run economic growth.
Step 8: Create a Family System, Not Just a Plan
Money without shared values and communication often doesn't survive past the second generation (a well-documented pattern sometimes called "shirtsleeves to shirtsleeves in three generations").
- Write down and communicate your values , not just your asset allocation — why the money exists and what it's meant to do.
- Hold regular family financial meetings as children become adults, so decisions and expectations aren't a surprise.
- Consider a family mission statement or governance structure for larger estates — this can include how a family business or shared assets will be managed by multiple heirs.
- Choose the right executors/trustees — capable, trustworthy people (or institutions) to manage the transition, not just the closest relative.
Step 9: Review and Adjust Regularly
- Revisit your estate plan, beneficiaries, and investment allocation every 1–3 years or after major life events.
- Reassess tax law changes that affect your strategy — these shift more often than most people expect.
- As net worth grows, the plan should evolve from "personal financial stability" toward more sophisticated tools (trusts, business succession planning, philanthropic vehicles like donor-advised funds or foundations).
Quick Reference
- 1Stabilize (emergency fund, insurance, debt payoff)
- 2Grow and protect income
- 3Save/invest consistently and automatically
- 4Protect assets (insurance, legal structure, estate documents)
- 5Minimize transfer taxes and costs
- 6Educate heirs
- 7Build real ownership (business, real estate, equities)
- 8Align the family around shared values and communication
- 9Review regularly
This guide provides general financial education, not personalized financial, tax, or legal advice. Laws and tax rules vary by country and change over time — work with a qualified financial advisor, tax professional, and estate attorney for decisions specific to your situation.